Near-term weakness in Las Vegas and Macau is likely to overshadow MGM Resorts International’s long-term value following People Inc.’s withdrawal of its takeover bid, according to Seaport Research.
In a September 24th note, senior analyst Vitaly Umansky said Seaport had been skeptical that the takeover would be completed, partly because of MGM’s assessment of its own value.
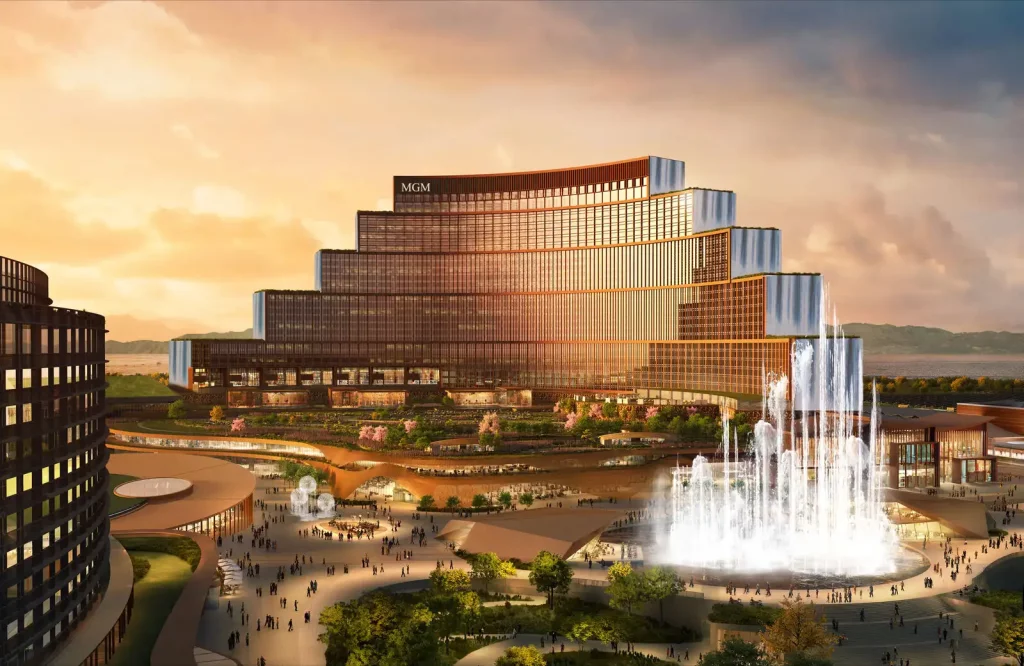
He singled out the group’s future Japan project, ‘which has not been captured by MGM’s trading price.’
MGM’s board has continued to emphasize its international businesses following the withdrawal. Chairman Paul Salem cited MGM China and the opportunity ahead with MGM Osaka as part of the group’s strategy to increase shareholder value.

Macau revenue growth faces margin pressure
Seaport lowered its Macau market estimates for the second half of 2026 and for 2027, citing slower near-term growth.
For MGM China, the brokerage forecasts full-year 2026 gross gaming revenue (GGR) growth of 3 percent and net revenue growth of 2 percent. However, it expects property EBITDA to decline 2.9 percent, with the corresponding margin narrowing to 27.4 percent from 28.8 percent in 2025.
The model also projects higher corporate expenses and license fees, adding to pressure on earnings after those deductions.
The outlook differs across gaming segments. Seaport forecasts MGM China’s mass-market GGR to rise 5.3 percent this year, while VIP GGR falls 22.7 percent. VIP play would account for 9.4 percent of total GGR, down from 12.5 percent in 2025.
The projected VIP decline includes both lower betting volume and a lower casino win rate. Rolling chip volume is forecast to fall approximately 5.7 percent, while the win rate is expected to ease to 3.1 percent from 3.7 percent.
Similarly, the mass-market forecast includes a higher hold rate: table drop is projected to increase approximately 1.1 percent, while hold rises to 26.6 percent from 25.5 percent. The stronger GGR growth therefore does not translate directly into an equivalent increase in betting volume.
Seaport’s quarterly model points to a weaker fourth quarter for MGM China, with net revenue expected to fall 3.7 percent year-on-year and adjusted property EBITDA declining 9.1 percent.
‘While we believe there is long-term value in MGM (across most of its businesses, including US casinos, Macau, Japan and BetMGM), the near-term weakness in Las Vegas and Macau will trump long-term value,’ Umansky wrote.
Another offer remains possible
The assessment follows Barry Diller’s People Incorporated withdrawing its June 1st proposal to acquire the MGM shares it did not already own for $48.30 each. MGM said on September 23rd that it would remain a standalone company after several months of negotiations.
Despite the withdrawal, Seaport expects People to continue acquiring MGM shares and MGM to resume its own share repurchase program, which was paused after the takeover proposal was announced.
‘In our view, it is possible that People comes back with another offer in the future,’ Umansky wrote.
People retains approximately 27 percent of MGM. Diller said the company remained “open to and interested in the possibility of a strategic transaction with MGM Resorts.”