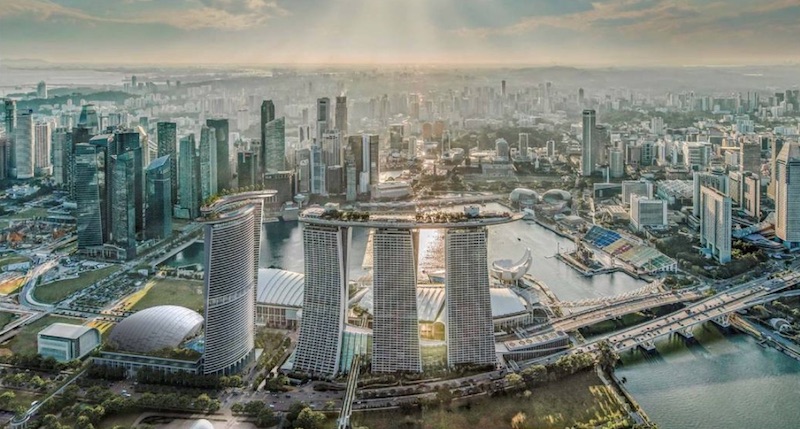
Moody’s Ratings has maintained a stable credit outlook for Las Vegas Sands (LVS) despite the group’s substantial development commitments, citing ‘strong liquidity’ and the expected earnings contribution from the Marina Bay Sands expansion.
The ratings agency on Thursday affirmed LVS’s investment-grade Baa3 senior unsecured rating and the Baa2 rating of its Macau subsidiary, Sands China. Both companies retained stable outlooks.
Moody’s expects LVS to keep debt at around three times EBITDA while carrying out its major developments, including the Marina Bay Sands expansion in Singapore.
The agency said the expansion should attract a ‘considerable amount’ of additional visitation upon completion, generating ‘considerable earnings’ and strengthening LVS’s ability to reduce debt.


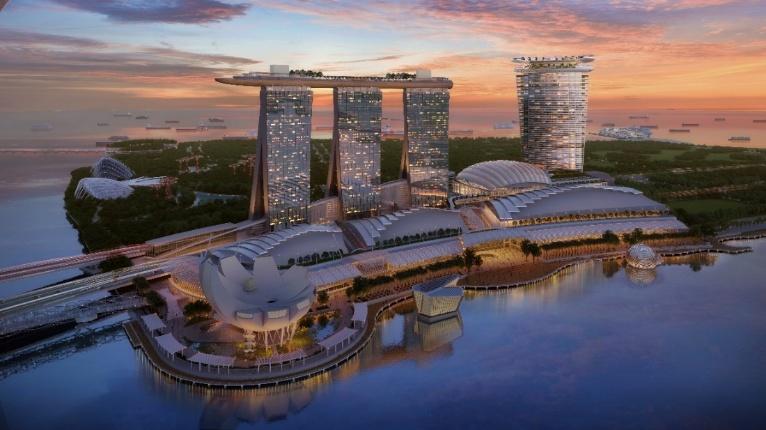
Marina Bay Sands generated an adjusted property EBITDA margin of approximately 50 percent in the first half of 2026. Moody’s also cited the established market positions of the group’s integrated resorts and favorable long-term gaming demand in Singapore and Macau.
As of June 30, LVS held $3.38 billion in unrestricted cash and cash equivalents, along with $4.26 billion in available capacity under its credit facilities.
Marina Bay Sands separately had access to approximately $4.68 billion under a $5.88 billion delayed-draw term loan facility. Moody’s said it expects LVS to comply with its debt covenants and manage upcoming maturities in a timely manner.
However, the agency identified LVS’s substantial development commitments as a key credit concern. Further integrated resort investments could lead to periods of higher debt if they are financed materially through borrowing.
Continued dividend payments, share repurchases and the use of secured debt to fund developments could also constrain the group’s credit profile.
Moody’s warned that the rating could come under pressure if liquidity deteriorates or the earnings recovery at LVS’s Macau operations fails to continue. A downgrade could also follow if debt remains above three times EBITDA for an extended period.
An upgrade would require LVS to reduce adjusted gross debt to two times EBITDA or lower, while maintaining consistent revenue growth and stable or improving margins.