Sands China has locked in $1 billion of new senior unsecured debt split across 2032 and 2033 maturities, and will use the money to retire a $700 million bond that was not due until March 2027.
The Macau arm of Las Vegas Sands confirmed the final terms in an inside information announcement to the Hong Kong Stock Exchange on Wednesday. It signed the purchase agreement on October 27, New York time, with Barclays Capital, BofA Securities and Goldman Sachs acting as representatives for a wider group of initial purchasers that includes several Macau bank branches.
Two tranches with coupons above 6%
The larger tranche is $700 million of 6.400% notes maturing on January 8, 2032, sold at 99.851% of face value. The second is $300 million of 6.700% notes running to November 8, 2033, priced at 99.954%. Both series pay interest twice a year, with the first coupons falling on January 8 and May 8, 2027 respectively. Settlement is scheduled for November 3, subject to customary conditions.
The paper is being placed only with qualified institutional buyers under Rule 144A and with investors outside the United States under Regulation S. There is no public offer in Hong Kong, although the company has received an eligibility letter from the exchange and intends to list the notes there.
Where the money goes
Sands China expects net proceeds of roughly $989 million. Combined with cash on hand, that will fund full redemption of its $700 million of 2.300% notes due March 8, 2027, repayment of whatever is drawn on its 2024 revolving credit facility, a HK$19.5 billion line worth about $2.49 billion, and general corporate spending including capital expenditure. The board said the issue would lengthen the group’s maturity profile and add to its liquidity.
Bondholders also receive a Macau specific safeguard. If a change to the Macao Gaming Law or a decision by a gaming authority leaves the group unable to run its casinos in broadly the same way for at least 30 straight days, and that materially hurts the business, holders can demand that Sands China buy back their notes at par plus accrued interest.
Ratings agencies see leverage holding steady
Fitch Ratings and S&P Global Ratings each assigned a BBB rating to the new notes and expect leverage to stay broadly unchanged after the deal, GGRAsia reported, citing memos issued on Tuesday. S&P noted that the refinancing moves the company’s next bond maturity out to August 2028, when $1.9 billion comes due.
CreditSights estimated gross and net leverage at about 2.8 times and 2.3 times at the end of September, with total debt near $6.3 billion and cash of $1.1 billion. The research firm also calculated that Sands China’s adjusted EBITDA dropped 12% year on year to $529 million in the third quarter, a period in which Macau casino GGR fell 3.8%. The parent company’s Singapore resort had a softer quarter too, with Marina Bay Sands EBITDA down 20.6%.
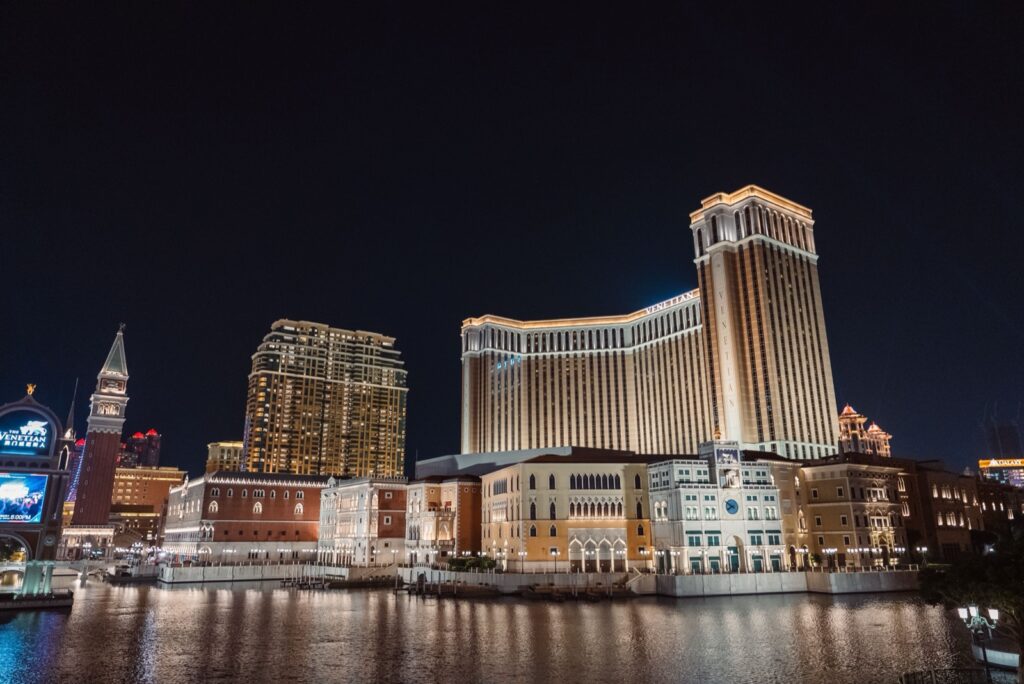
In Macau the company operates Sands Macao on the peninsula and, on the Cotai Strip, The Venetian Macao, The Plaza Macao, The Parisian Macao and The Londoner Macao. Its subsidiary Venetian Macau Limited holds one of the six Macau gaming concessions, effective since January 1, 2023.