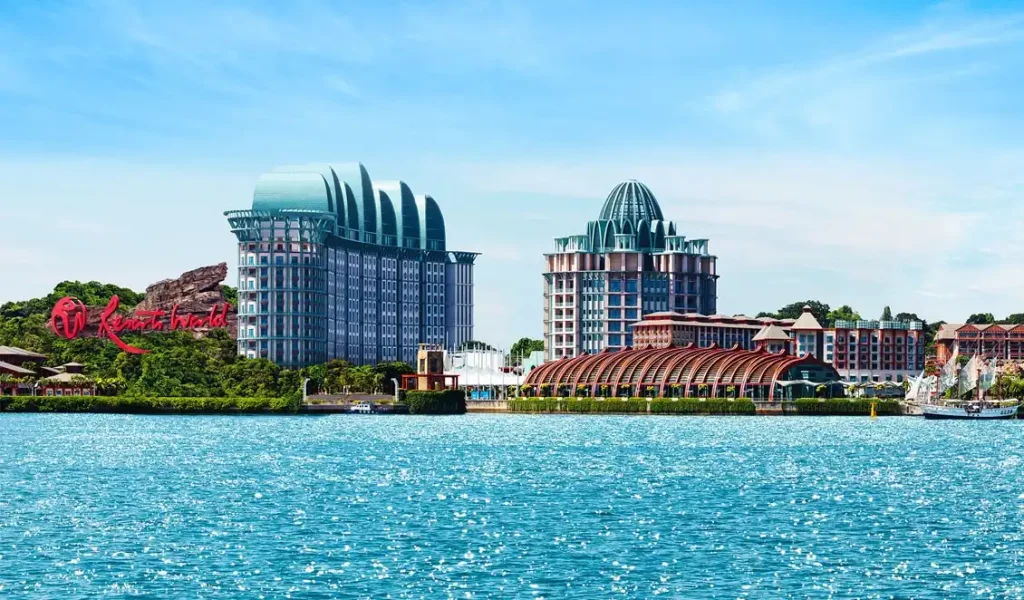
Maybank analyst Samuel Yin Shao Yang described Genting Singapore’s second-quarter operating recovery as largely a normalization following a weak start to the year, with the brokerage cutting its 2026 earnings estimate by 17 percent.
Maybank also lowered its earnings estimates for 2027 and 2028 by 15 percent and 14 percent, respectively.
The revisions were mainly attributed to higher expected depreciation and amortization and lower net interest income. Maybank’s EBITDA estimates were little changed, indicating that the cuts did not represent a comparable downgrade to its operating outlook.
The brokerage described the latest performance as ‘normalisation but not a re-rating,’ with more sustained growth still dependent on Resorts World Sentosa’s (RWS) expanded offerings attracting additional visitors and gaming revenue.
Recovery follows weak first quarter
Genting Singapore’s adjusted EBITDA rose 18 percent quarter-on-quarter and 12 percent year-on-year to SG$210.8 million ($164 million) in the second quarter.
Maybank estimated that VIP volume recovered 21 percent sequentially, while mass-market gross gaming revenue increased 2 percent. The improvement lifted RWS’s estimated share of Singapore’s VIP market to 36 percent from 19 percent in the first quarter, while its mass-market share edged up to 27 percent from 26 percent.
However, the year-on-year comparison remained mixed. VIP volume was still 26 percent lower, although higher-margin mass-market GGR increased 14 percent and supported the EBITDA improvement.
The sequential market-share gains also came from a particularly weak first-quarter base. Maybank said Genting Singapore had characterized the earlier performance as ‘self-inflicted,’ with the second-quarter results showing that operations had since stabilized.
Quarterly revenue increased 1 percent year-on-year but fell 2 percent sequentially to SG$596 million ($464 million). Gaming revenue was broadly unchanged from a year earlier and edged down from the first quarter.
Core net profit reached SG$92.9 million ($72.3 million), down 6 percent year-on-year despite increasing 33 percent sequentially.

RWS 2.0 remains key to sustained growth
Yin said a more meaningful improvement would depend on RWS 2.0 generating stronger visitation and gaming revenue from 2027.
Genting Singapore has invested approximately SG$1.8 billion ($1.40 billion) in the expansion to date, according to Maybank.
Several new and refreshed attractions have already opened, including Singapore Oceanarium, lifestyle destination WEAVE, Illumination’s Minion Land and luxury hotel The Laurus.
The company is planning further upgrades to Hotel Michael, Crockfords Tower, its casino, dining venues and other guest-facing areas. New and refreshed facilities are expected to be introduced progressively during 2027 and 2028.
For the first half of 2026, Genting Singapore reported a 34 percent decline in net profit to SG$156.1 million ($122 million). Adjusted EBITDA fell 8 percent to SG$389.8 million ($304 million), while revenue remained broadly stable at SG$1.20 billion ($939 million).