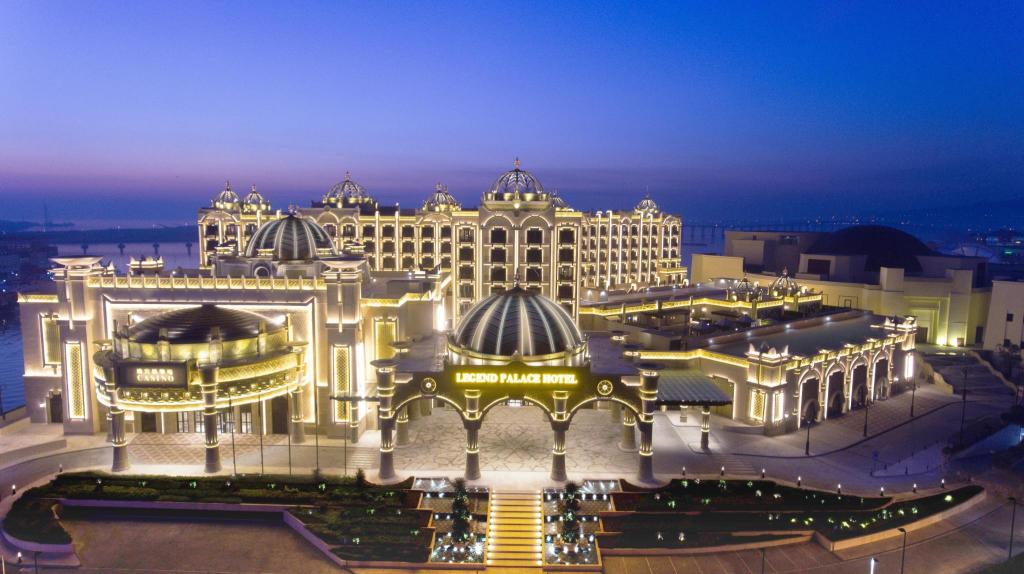
Macau Legend Development returned to positive adjusted EBITDA in the first half of 2026, its first full six-month period without gaming revenue, but its auditor declined to express a conclusion on the interim accounts, citing doubts over the group’s ability to continue as a going concern.
Revenue from continuing operations, now entirely non-gaming, rose 2.7 percent year-on-year to HK$172.65 million ($22.1 million). Adjusted EBITDA swung to a profit of HK$8.8 million ($1.1 million) from a loss of HK$0.1 million ($13,000) a year earlier, which the company attributed mainly to a HK$5.6 million ($718,000) reduction in staff costs and a HK$4.3 million ($551,000) cut in inventory costs.
The comparison excludes gaming. Legend Palace Casino, operated under a service agreement with SJM Resorts, generated HK$175.1 million ($22.4 million) in the first half of 2025 before the two sides terminated the arrangement on November 13th that year.
Net loss narrowed to HK$136.8 million ($17.5 million) from HK$1,420.8 million ($182.2 million), when the group booked HK$1,272.2 million ($163.1 million) in impairments on its Macau assets ahead of the casino closure. No further impairment was recognized in the latest period.
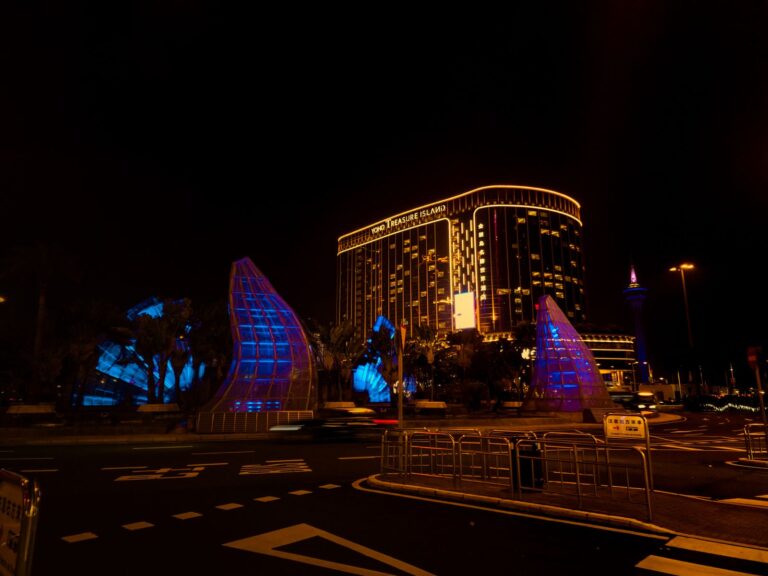
Hotel room income rose HK$6.2 million ($795,000) after all Legend Palace Hotel rooms were sold to third parties rather than partly used to support gaming. Occupancy at the property was 91.2 percent, with an average daily rate of HK$929 ($119). At Harbourview Hotel, occupancy improved to 91.0 percent but the average daily rate fell to HK$671 ($86) from HK$766 ($98).
Baker Tilly Hong Kong issued a disclaimer of conclusion on the interim statements, pointing to ‘multiple uncertainties relating to going concern.’
The group reported net current liabilities of HK$2,681.2 million ($343.7 million) and cash and bank balances of HK$37.9 million ($4.9 million) as at June 30th. Total bank and other borrowings of HK$2,391.2 million ($306.6 million) fall due within 12 months or are repayable on demand.
Macau Legend remained in breach of covenants on minimum net assets and its indebtedness ratio, leaving HK$2,051.8 million ($263.1 million) in bank borrowings immediately repayable if the lenders demand it. No such demand had been made as at the date of the announcement.
A debt restructuring covering repayment dates and certain key loan terms was agreed in principle with the banks in August 2026, though a formal agreement was still pending execution. Net gearing rose to 165.6 percent from 161.2 percent at the end of 2025.