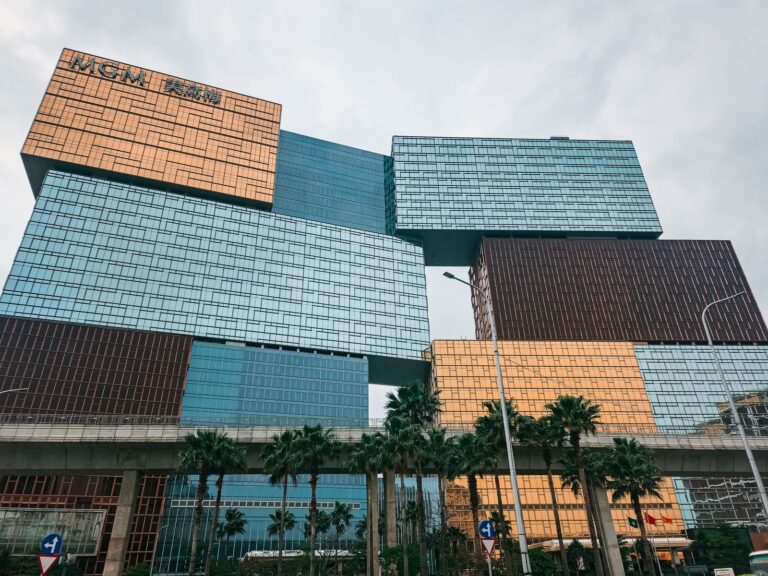

MGM China’s 2Q26 adjusted EBITDA exceeded market expectations, with analysts pointing to controlled player reinvestment and lower operating costs despite weaker gaming volumes.
Adjusted EBITDA fell 7.4 percent year-on-year to HK$2.33 billion ($298 million). Jefferies said the result was 8 percent above market estimates, while CLSA placed it 1 percent above its forecast and the Bloomberg consensus.
The difference reflects the separate consensus comparisons used by the two brokerages.
CLSA analyst Jeffrey Kiang said player rebates and reinvestment, as well as daily operating expenses at MGM Cotai, were below the brokerage’s forecasts, ‘signaling good discipline’.
Although MGM China’s daily property operating expenses increased 9 percent year-on-year, its adjusted EBITDA margin remained at 27 percent. CLSA said this was within management’s targeted high-20s range.
The brokerage also estimated that MGM China’s luck-adjusted EBITDA declined by a more moderate 3 percent year-on-year. Both MGM Macau and MGM Cotai recorded VIP win rates of 2.8 percent, below the normal level of about 3 percent.
Jefferies analysts Anne Ling and Jingjue Pei said the World Cup’s impact on Macau’s June gaming volumes was a ‘transitory event rather than a secular shift’.
The brokerage noted that average daily visitation and normalized gross gaming revenue (GGR) at MGM’s properties during July 22nd–26th had already exceeded their 1Q26 pre-World Cup levels. The wider Macau market had also recovered to nearly its 1Q26 level.
CLSA reported a similar recovery, saying MGM China’s visitation and luck-neutral GGR exceeded the 1Q26 run rate during the third week of July, supported by pent-up demand following the tournament.
Jefferies also highlighted MGM China’s approach to the premium segment. The brokerage said management viewed competition as being driven by the overall customer ‘package’, including products, services and innovation, rather than promotional reinvestment alone.
Recent investment has included new suites and premium gaming areas at both MGM Macau and MGM Cotai. Jefferies said the company had started design work for about 100 additional suites at MGM Macau as it seeks to respond to changing preferences among premium customers.
CLSA said MGM China’s recurring cash flow, balance sheet and relatively high margins supported its valuation. Jefferies maintained a Buy rating on the company, while CLSA retained an Outperform rating.