Wynn Macau’s stronger second-quarter earnings improved its credit position and ability to service debt, prompting CreditSights to turn more positive on the casino operator’s US-dollar bonds despite the prospect of heavier capital expenditure in 2027.
The credit research firm upgraded its recommendation on Wynn Macau’s bonds to tactical Outperform from Market Perform. The change is an investment recommendation rather than an upgrade to the operator’s formal credit rating.
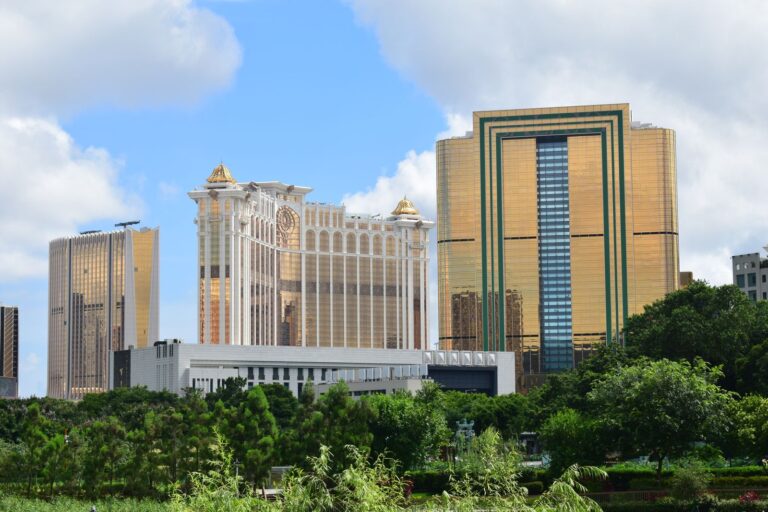
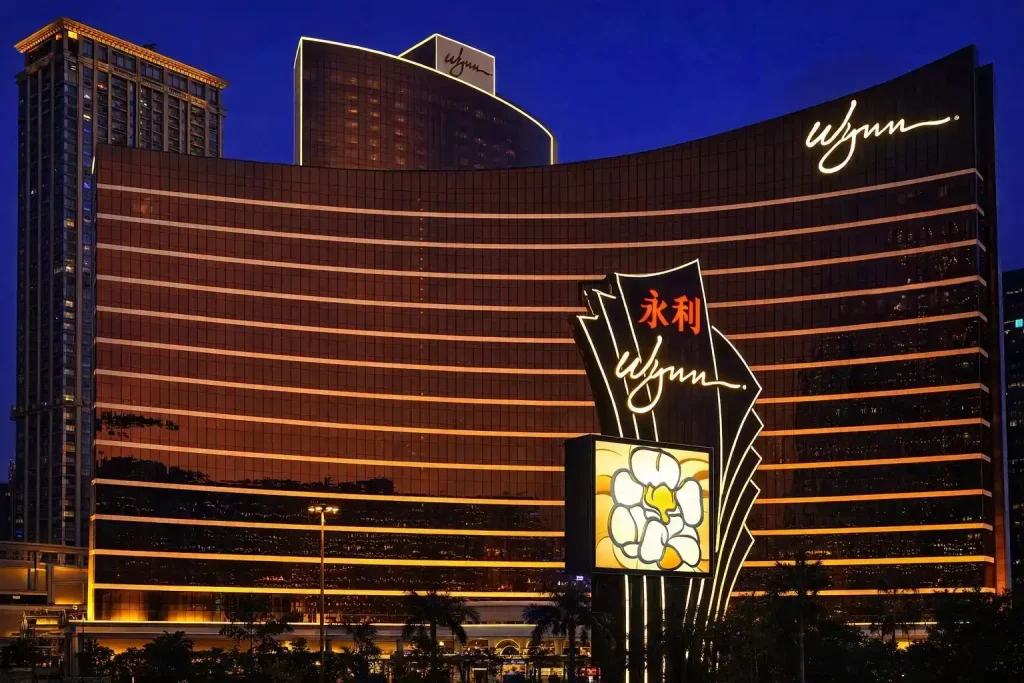
Wynn Macau’s total revenue rose 14 percent year-on-year to $1 billion in the second quarter, driven largely by Wynn Palace, where revenue increased 21 percent. Revenue at the Wynn Macau property rose by a more moderate 2 percent.
Adjusted property EBITDAR increased 17 percent to $297 million, while the margin improved by 0.9 percentage points to 29.6 percent. CreditSights estimated that unfavorable VIP hold reduced adjusted property EBITDAR by about $9 million during the period.
The stronger earnings reduced Wynn Macau’s debt relative to its operating performance, although total debt remained broadly unchanged at $5.8 billion. CreditSights said the improvement came from higher adjusted property EBITDAR rather than debt repayment, with leverage still above pre-pandemic levels.
The firm estimated that Wynn Macau generated between $110 million and $130 million in free cash flow during the quarter. It expects cash generation to remain positive in the second half of 2026 but does not anticipate material debt reduction this year.
However, CreditSights identified the increase in development spending as the ‘main headwind’ for Wynn Macau. The operator lowered its 2026 capex guidance to between $350 million and $400 million from $400 million to $450 million, but raised its 2027 range to between $750 million and $800 million.
The higher spending is linked to the expansion of Wynn Palace, which was approved by the Macau government in July. The development includes The Enclave five-star hotel, an event and entertainment center and a theatre with a resident show.
Construction of the entertainment center and theatre is scheduled to begin in the third quarter of 2026, while work on The Enclave is expected to start by the end of the year. Activity this year will largely involve piling and early development works, with the major spending ramp-up expected from 2027.
CreditSights said Wynn Macau’s focus on the premium segment had ‘paid some dividends’ through improved margins and market share. The firm estimated the operator’s share of Macau gaming revenue increased to 13.7 percent in the second quarter, from 12.5 percent in the previous quarter and 11.9 percent a year earlier.
It also expects further revenue and adjusted property EBITDAR growth in the third quarter, supported by the continued ramp-up of Chairman’s Club and recovering gaming volumes following the World Cup.