
Wynn Palace’s unusually high mass-table hold drove much of its second-quarter outperformance, prompting analysts to assess how much of the improvement can continue as gaming volumes recorded more moderate growth.
The Cotai property recorded a mass-table hold rate of 29.7 percent in the three months to June 30th, compared with 22.3 percent a year earlier. Seaport Research Partners estimates its normal theoretical range at between 23 percent and 25 percent.
Deutsche Bank estimated that the elevated hold added approximately $100 million to Wynn Palace’s gross gaming revenue during the quarter.
The difference between volume and revenue growth illustrates the impact. Mass-table drop at Wynn Palace rose 3 percent year-on-year to $1.9 billion, while mass-table revenue increased 36.9 percent to $563.3 million.
Property net revenue rose 21.1 percent to $653.4 million, while adjusted property EBITDAR increased 28.2 percent to $201.5 million.

Part of hold increase may be structural
Deutsche Bank analyst Steven Pizzella noted that the brokerage does not normally adjust its estimates for mass hold.
‘We expect investors to focus on the sustainability of these results moving forward,’ the brokerage said.

Seaport offered a more nuanced interpretation. Senior analyst Vitaly Umansky wrote that Wynn Palace’s theoretical hold had ‘gravitated upwards’ because of increased side betting carrying a higher house edge and likely longer playing time, partly associated with the expanded Chairman’s Club.
This suggests that some of the increase may be structural, although the reported rate remained above Seaport’s estimated theoretical range. Hold at the property was already elevated at 26.6 percent in the first quarter.
The Chairman’s Club remains in its ramp-up phase. Deutsche Bank said the expanded premium gaming area could attract new customers and increase playing time among existing patrons.
VIP weakness offsets mass performance
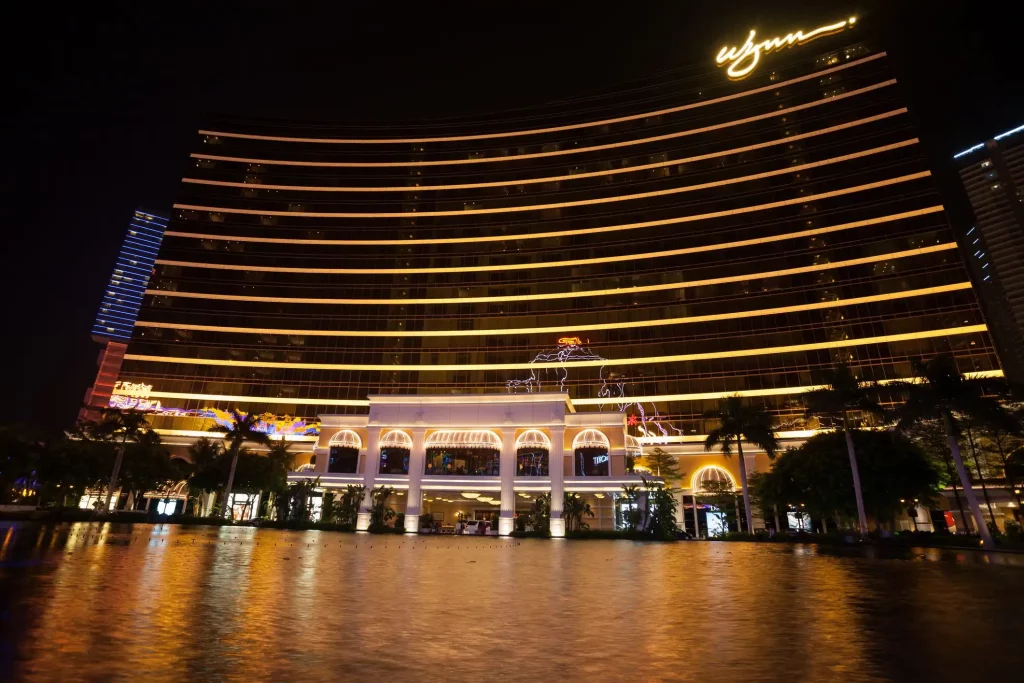
VIP activity moved in the opposite direction. Combined rolling-chip volume at Wynn Macau’s two properties fell 36.8 percent year-on-year to $3.2 billion.
VIP hold stood at 2.92 percent, below the company’s expected range of 3.1 percent to 3.4 percent. The unfavorable result reduced adjusted property EBITDAR by approximately $9 million, according to Deutsche Bank.
Across Wynn’s Macau operations, adjusted property EBITDAR reached $297 million, up from $254 million a year earlier.
Estimates of Wynn’s Macau market share vary because of differences in methodology. Jefferies placed its second-quarter share at 13.9 percent, up 1.9 percentage points year-on-year and 1 percentage point sequentially.
Seaport’s adjusted calculation put the share at 14.6 percent, compared with 12.7 percent a year earlier and 13.7 percent in the first quarter. The brokerage expects Wynn’s share to remain in the low-14-percent range over the next several quarters.
Management told analysts that rolling-chip volume and mass-table drop were slightly lower year-on-year early in the third quarter due to the FIFA World Cup and normal seasonality. Business improved in late July and continued strengthening into early August as summer holiday travel picked up.